Multi-Entity Cash Flow Framework & Tax Strategy
Financial Services, Multi-Entity Cash Flow, Tax Strategy
Which Entity Has the Cash? A Practical Framework for Multi-Entity Cash Flow Clarity
A clear, practical framework to help multi-entity business owners see where cash sits, what is truly available, and how every cash decision connects to tax strategy and long-term stability.
Multiple bank accounts, several legal entities, and a growing business are signs of progress — but they can also create a new kind of uncertainty. You can log in to the bank and see balances, yet still struggle to answer a simple question with confidence: Which entity actually has the cash, and how much of it can you use?
Operating companies, holding companies, real estate LLCs, investment entities, and IP companies all serve a purpose. The challenge is that as structure multiplies, clarity often disappears. Payroll, taxes, intercompany loans, and future commitments all sit inside those balances, quietly limiting what is truly available. Stress builds not because you are failing, but because your structure has outgrown your current reporting rhythm.
Multi-Entity Cash Flow Clarity: Beyond Logging Into the Bank
For multi-entity owners, cash flow clarity means understanding not just how much cash exists, but who owns it, what it is earmarked for, and how it can move without breaking legal, accounting, or tax rules. It is the difference between glancing at a total balance and being able to make a distribution, fund an investment, or sign a lease with calm certainty instead of guesswork.
Cash Visibility vs. Cash Clarity
A consolidated view that shows, for example, $300,000 across several accounts feels reassuring. That is cash visibility — you know what sits in the bank. But when you look closer, you may find that a large portion is already spoken for: funds belonging to a real estate LLC, payroll reserves, upcoming tax payments, intercompany loans, or committed capital expenditures. Once those are accounted for, the cash you can safely deploy may be far lower than the headline number.
Cash clarity goes further. It tells you:
Which legal entity owns each dollar.
What cash is reserved for payroll, taxes, and debt service.
What can be moved, under what conditions, and what must remain protected.
That distinction — visibility versus clarity — sits at the center of confident financial decision-making for multi-entity owners.
The Five-Step Cash Clarity Framework
1. Map Where Cash Sits Today
Clarity begins with a complete map. List every entity and every location where cash enters, leaves, or sits — bank accounts, credit cards, merchant accounts, tax reserves, escrow, lines of credit, and payment processors. For each, note the legal name, business purpose, and tax classification, then label each account by entity. This exercise often reveals hidden or misused accounts and surfaces the first blind spots in your structure.
A single, accurate map of all entities and accounts is the starting point for real cash clarity.
2. Separate Bank Cash From Usable Cash
Once the map is complete, calculate the cash position for each entity using a simple structure: bank cash – committed expenses – tax reserves – debt obligations – minimum operating reserve = usable cash. The minimum reserve will differ for an operating company, a real estate LLC, or a holding company, but the logic is the same — not all cash is deployable.
A rolling 13-week cash forecast for each active entity turns this snapshot into a living tool. Track opening cash, expected receipts, intercompany inflows, payroll, vendor payments, debt service, taxes, and capital expenditures. The forecast does not need to be complex — it needs to be updated regularly so you can move from “Can we afford this?” to “Which entity can fund this, and under what conditions?”
3. Separate Owner Draws, Distributions, and Intercompany Transfers
Money moving between accounts is not automatically profit. It may be an owner draw, shareholder or member distribution, intercompany loan, capital contribution, management fee, expense reimbursement, or tax payment. Each category carries different accounting and tax consequences and tells a different story about business health. For pass-through entities in particular, taxable income and cash available for distribution can diverge sharply.
Every transfer should have a clear purpose, consistent accounting treatment, supporting documentation, and a tax strategy behind it. Your tax advisor should review these decisions in the context of entity classification, ownership, basis, and applicable rules. Cash decisions are far easier to manage when they are documented before they become confusing.
4. Establish an Intercompany Clearing Rhythm
Many multi-entity problems live in the gaps between entities — when one company pays another’s bills, personal cards cover business expenses, or shared employees and vendors are paid by a single entity. These choices may be practical in the moment, but over time they blur cash ownership and weaken your books.
A regular intercompany clearing process restores order. At least monthly, review which entity paid expenses for another, who owes money, who is owed money, how shared costs are allocated, whether management fees are supported by agreements, and whether loans are clearly separated from distributions. You do not need to move cash every time, but you do need a reliable record and a consistent rhythm so balances do not linger unresolved until tax season.
5. Build One Owner’s Dashboard
Finally, consolidate what matters into a single owner’s dashboard. Instead of five bank logins and scattered spreadsheets, you should have one view that shows cash by entity, usable cash by entity, minimum reserves, tax reserves and upcoming payments, intercompany receivables and payables, debt obligations, 13-week forecasts, planned distributions, trapped or restricted cash, and profitability by entity. The dashboard should help you answer three questions quickly: What do we have? What can we use? What needs protection?
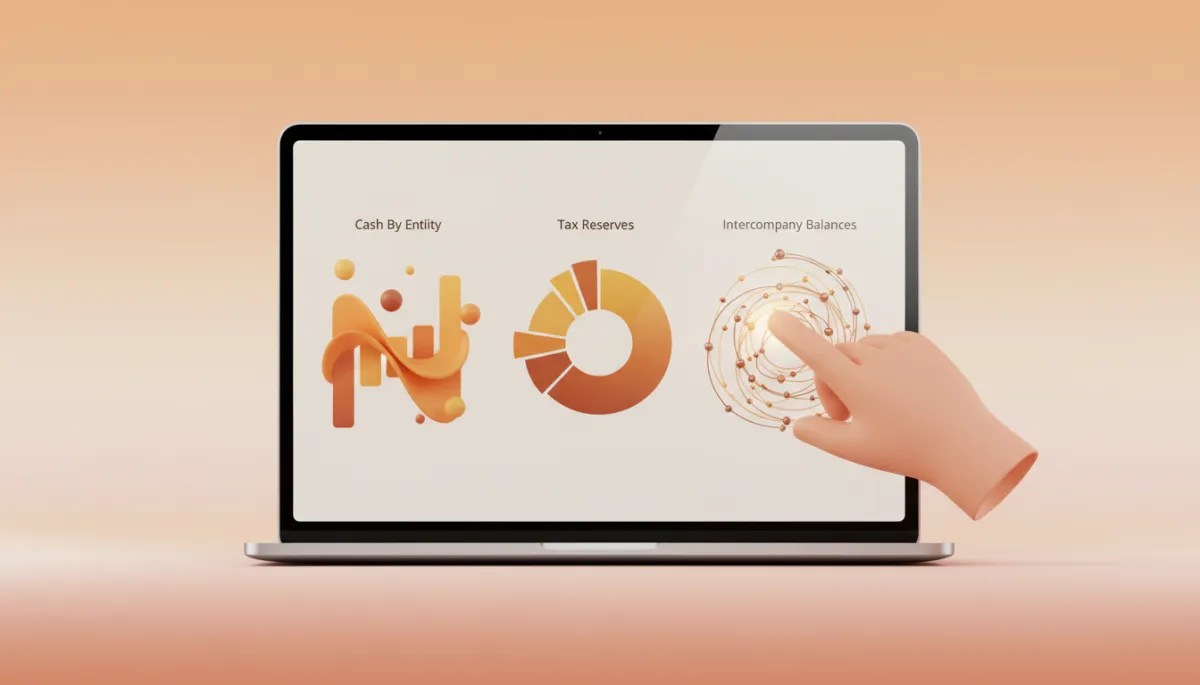
A concise owner’s dashboard turns complex multi-entity data into decisions you can make with confidence.
Cash Clarity and Tax Strategy Are the Same Conversation
In a multi-entity environment, cash planning and tax planning cannot be separated. If an operating company generates profit, someone must plan for the tax on that profit — even if the cash has not yet been distributed. If cash is moving to a holding company, the transfer must match the legal and tax structure. If owners receive distributions, the business needs to know whether tax reserves remain adequate afterward.
A year-round tax strategy should consider current and projected taxable income, estimated payments, owner compensation, distribution capacity, retained cash needs, equipment purchases, retirement contributions, depreciation opportunities, multi-state obligations, intercompany activity, and future entity changes. The key questions become: Which entity generates the income, where is the cash to pay the tax, when will payments be due, and will distributions create liquidity pressure elsewhere in the structure?
A Practical Monthly Meeting Agenda
One structured meeting each month can keep your framework active and your decisions grounded. With the right information prepared in advance, this review does not need to be lengthy — it needs to be disciplined. A practical agenda includes:
Reviewing bank cash by entity, compared to minimum reserves.
Comparing actual cash movements to the 13-week forecast.
Confirming upcoming payroll, debt service, and tax obligations.
Reviewing intercompany balances and clearing activity.
Identifying cash that can be safely distributed or invested.
Updating tax projections based on year-to-date results.
Deciding what questions require professional review or adjustment.
A focused monthly review turns your cash framework into an ongoing management habit, not a one-time project.
When to Get Professional Help
It is time to seek support when transfers between entities are hard to explain, personal funds routinely cover business expenses, entities share employees or vendors without clear allocation, or your books show profit while your bank balance feels tight. If tax estimates seem disconnected from cash flow, or if multiple advisors do not communicate about structure and strategy, you are likely carrying more risk and stress than necessary.
A coordinated advisory team can connect accounting, tax strategy, business structure, and personal financial decisions into one coherent practice. When books inform tax positioning, tax strategy informs structure, and structure informs cash flow planning, you move from reactive problem-solving to proactive, aligned decision-making across every entity you own.
No More Guessing: Every Dollar With a Clear Home
You should not need to reconstruct your financial position every time you consider a hire, a purchase, an investment, or a distribution. With a practical framework in place, you can see where the cash sits, what it is committed to, which entities are profitable or under pressure, what can move, and what must stay protected. Peace, ease, and clarity are not abstract goals — they are the natural result of a reliable cash and tax rhythm.
Every entity in your structure has a purpose. Every dollar should have a clear home. When you can answer, with confidence, “Which entity has the cash — and what can we safely do with it?” you have moved beyond visibility into true multi-entity cash flow clarity.